Rain Instant Pay

Screenshots
Details
- Rating
- 4.22K reviews
- Version
- 2.7.1
- Developer
- Rain Technologies Inc
Analysis by Norviv
I approached Rain Instant Pay as a practical workplace-finance app rather than as a general banking replacement. Its purpose is straightforward: it helps eligible employees access an employer benefit connected with getting paid. That makes the app potentially useful at a very specific moment—when your regular payday is still ahead, but an everyday expense cannot wait.
The important point is that the app’s usefulness depends on your employer’s relationship with Rain. Installing it alone does not turn it into a universal cash-advance service. In my view, that distinction should shape your expectations from the first screen. If your workplace supports the benefit, Rain can become a convenient part of your pay routine. If it does not, the app is unlikely to solve an immediate money problem simply because it is installed on your phone.
How Rain Instant Pay fits into real working life
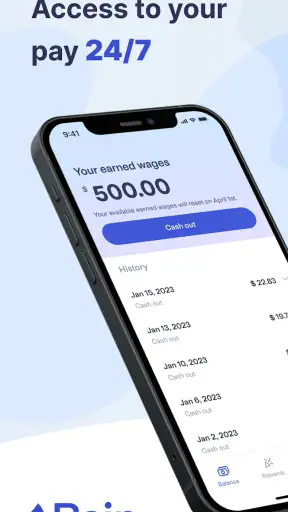
Rain Technologies Inc developed this free Business app for people who want to use an employer-linked instant-pay benefit. The store listing presents it as a way to unlock employer benefits, while its short description focuses on instant pay. Those two ideas belong together: the app is less about managing every part of your financial life and more about giving you access to a workplace feature when you need it.
I would describe the experience as an access point rather than a full financial command center. That is a useful distinction when comparing it with ordinary banking apps, payroll portals, budgeting tools, or standalone borrowing services. A bank app normally centers on balances, transfers, cards, and account history. A payroll portal usually focuses on schedules, documents, and employer records. Rain sits in a narrower space, concentrating on the connection between earned pay and earlier access.
That narrow purpose is also why the app can feel relevant immediately for one person and almost irrelevant to another. A worker whose employer offers the benefit may see a clear reason to keep Rain available. Someone outside that employer network may find that the app does not replace a bank account, a budgeting app, or a conventional emergency-fund strategy.
The app is listed as free, so there is no purchase price to pay for downloading it. That is the clearest cost fact a prospective user can rely on. Free access, however, should not be confused with a promise that every use of an instant-pay benefit has identical financial terms. Before depending on an early-pay option, I would read the in-app explanation carefully and check the choices presented for your own employer arrangement.
This is especially important because a free download does not automatically mean that every possible transaction, timing option, or employer benefit works in the same way for everyone. Rain is the software layer; the practical value comes from the benefit available through your workplace. I would treat the app as a tool for accessing that arrangement, not as a blank check or an unconditional advance.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
The first setup decision is whether the benefit applies to you
For a new user, the most important early question is not whether the interface looks polished. It is whether your employer is supported and whether your employment details can be matched correctly. That makes accurate information during setup more important than rushing through the screens. A mismatch can create friction at exactly the moment you are trying to handle an urgent expense.
My practical advice is to install Rain before an emergency, not during one. Setting it up while your finances are calm gives you time to understand the available choices, confirm that the workplace connection is recognized, and learn where the relevant information appears. This is one of the less obvious advantages of treating the app as part of your financial preparation rather than as a last-minute rescue button.
I would also avoid assuming that an amount shown as available should automatically be taken. The useful habit is to compare the early access with your next normal paycheck and your upcoming fixed expenses. If using the benefit simply moves a shortage forward, the app may provide short-term relief without improving the underlying situation. Used selectively, it can be helpful; used automatically, it can make pay-cycle planning harder.
A realistic everyday scenario
Imagine that your car needs a repair late in the week, while your normal paycheck is scheduled for the following week. You have enough income coming in, but the timing is uncomfortable. In that situation, an employer-linked instant-pay app may help bridge the gap without forcing you to apply for a separate personal loan or move money between unrelated accounts.
I see the strongest case for Rain in precisely that kind of timing problem. The user already has employment income, already knows the next pay cycle is coming, and needs a controlled way to deal with a near-term bill. The app can be more direct than opening a new credit product, especially when the need is connected to an ordinary work-and-pay routine rather than a long-term financing goal.
There is a trade-off, though. If you use early access for a discretionary purchase, you may reach the next payday with less room than expected. I would reserve it for expenses where timing genuinely matters, then return to a normal budget as soon as possible. The app is most valuable when it solves a short gap, not when it becomes the default way to organize monthly spending.
What the app does well compared with familiar alternatives
Compared with a traditional payroll portal, Rain appears more focused on immediate access than on administrative records. A payroll system may be the better place to review formal employment information, while Rain is better suited to the moment when you are considering an employer-linked pay option. I would not expect one to replace the other.
Compared with a bank overdraft or a credit card, the appeal is that the feature is tied to employment benefits rather than presented as a general revolving credit tool. That can make the decision feel more connected to money you are already earning. Still, the user should not skip the terms simply because the money is related to wages. The timing and consequences of accessing pay early remain important.
Compared with a budgeting app, Rain is not where I would build a complete spending plan. A budgeting tool is designed to show categories, recurring commitments, and longer-term patterns. Rain is more targeted. Its strength is speed and relevance when the question is “Can I access part of my pay arrangement now?” Its weakness is that it does not, by itself, teach you whether doing so fits your whole month.
That division of labor suggests a sensible workflow. I would use Rain for the employer benefit, a bank app for ordinary account management, and a budgeting method for deciding whether early access is wise. Trying to make one narrow-purpose app perform all three jobs usually leads to poor financial visibility.
Where the value is strongest—and where it is limited
The main value is convenience. When a workplace benefit is available, having a dedicated mobile route can be easier than relying on a manual request or waiting for a payroll office to respond. The app also gives the benefit a place on your phone, which may make it easier to check your options at the time a bill becomes urgent.
Another useful quality is focus. Rain does not need to be a complicated financial dashboard to be worthwhile. For someone who wants a clear route to an employer-linked instant-pay feature, a focused app can be less distracting than a broad financial platform filled with tools they will never use.
Its limitation is equally clear: the app cannot create eligibility where the workplace benefit is not available. That makes Rain a poor choice for someone searching for a general-purpose way to borrow money, consolidate debt, monitor investments, or replace a checking account. Those needs call for different products and different safeguards.
I would also be cautious about using any early-pay feature as a substitute for an emergency fund. The app may help with timing, but it does not change the total pressure created by rent, utilities, transport, food, and other recurring costs. If the same shortfall appears every pay cycle, the better solution is likely a broader review of income and expenses rather than repeated early access.
Small habits that make the experience more useful
One practical habit is to check the app before a crisis, as mentioned earlier, but with a specific purpose: learn how your employer connection is represented and where you can review the relevant benefit information. Familiarity reduces the chance of making a rushed decision when you are tired or under pressure.
A second habit is to write down the normal payday impact before confirming an early-access choice. Even a simple note showing the bill today, the amount accessed, and the expenses due after payday can reveal whether the decision is a bridge or merely a delay. This is a more reliable test than judging the option by the available amount alone.
A third is to keep Rain separate from your long-term financial planning. I would not use the presence of an accessible benefit as a reason to lower savings goals or increase everyday spending. The feature is most helpful when treated as a backup for timing problems, not as extra monthly income.
Finally, I would review the information shown in the app each time the situation changes—such as a new employer, a different pay schedule, or an unfamiliar availability message. Workplace-linked tools are sensitive to employment context, so an assumption that was correct last month may not be correct after a job change.
Who should use it and who should skip it
Rain is a good fit for an employee whose workplace offers the relevant benefit, who sometimes faces short gaps before payday, and who is comfortable checking the financial consequences before using early access. It may also suit someone who prefers a dedicated mobile experience instead of handling every request through a payroll department or a general financial app.
I would recommend caution for users who already struggle to make a full paycheck last until the next one. Early access can feel convenient, but frequent use may turn a temporary timing issue into a repeating cycle. In that case, a budget review, direct conversation with an employer, or professional financial guidance may be more useful than relying on the app more often.
I would skip Rain as a primary solution if your goal is ordinary banking, detailed expense tracking, credit building, investing, or borrowing for a large purchase. The app’s narrow focus is a benefit when you need that exact workplace function, but it is a limitation when you need a complete financial toolkit.
What the current app profile tells me
Rain has been available since February 2020 and is currently listed at version 2.7.1. Its public store profile shows a 4.7 average from around 34 thousand ratings, with more than 500 thousand installs. Those figures suggest that the app has attracted a substantial user base and that many people find the concept useful, but popularity does not remove the need to understand your own employer arrangement.
The app is rated for Everyone, which makes its store classification broad and accessible. That age label should not be mistaken for financial advice, though. The responsible decision still depends on your employment situation, your pay cycle, and whether accessing money early helps or harms your monthly plan.
Because Rain is free to download, the initial commitment is low. I like that for an app whose usefulness depends heavily on workplace eligibility: you can explore whether it fits without paying an upfront purchase price. The real value decision comes later, when you decide whether an available instant-pay option is appropriate for a particular expense.
My verdict on the free download and the real value
I see Rain Instant Pay as a specialized tool with a sensible role, not as an all-purpose answer to financial stress. Its strongest use is a genuine short-term timing gap for an employee whose workplace supports the benefit. In that situation, the free app can offer a more direct path than a conventional loan application, a credit-card balance, or a manual payroll request.
The trade-off is that convenience can encourage impulsive access. The app is not a replacement for a bank, a budget, or savings, and it should not be judged by how much money appears available. I would judge it by whether it helps solve a specific need without making the next pay cycle unmanageable.
My recommendation is to try it if your employer offers Rain’s instant-pay benefit and you want to understand the option before you need it. Set it up calmly, read the details shown for your situation, and use it selectively. If your employer is not connected or your main need is broader financial management, I would skip it and choose a tool designed for that job instead.
Bottom line: Rain delivers the most value as a free, employer-linked access point for occasional pay-timing problems. It is worth keeping available for eligible workers who use it deliberately, but it is not the right choice for anyone expecting a complete banking service or a permanent solution to recurring money shortages.
Frequently Asked Questions
01What is Rain Instant Pay, and how does it work?
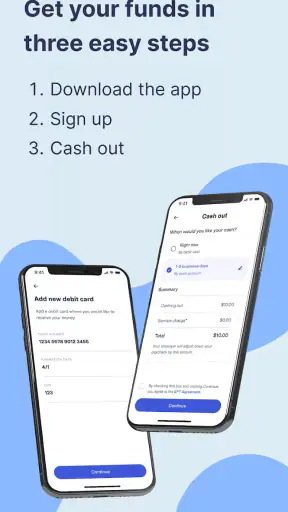
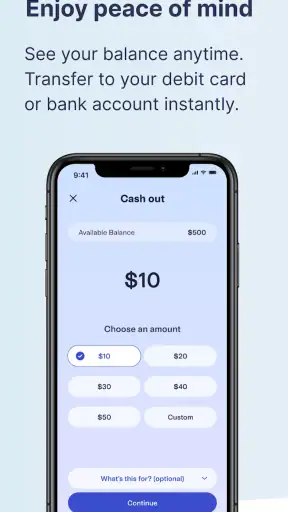
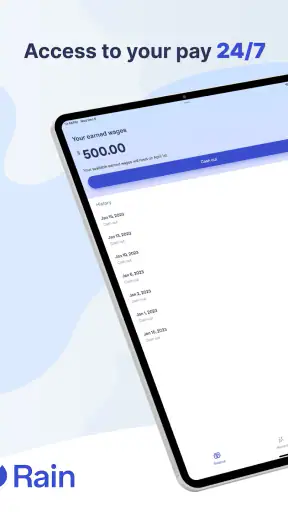
Rain Instant Pay is a financial app designed to help eligible employees access part of their earned wages before their regular payday. After creating an account and completing the required verification, the app may connect with an employer or payroll provider to show available earnings. Users can then request a transfer, although availability, limits, and processing times depend on employer participation and account eligibility.
02Is Rain Instant Pay available to everyone?
No. Access generally depends on whether your employer supports Rain Instant Pay and whether you meet the service’s eligibility requirements. The app may also require identity verification, an active payroll record, and sufficient earned wages. Availability can vary by workplace, location, employment status, and company policies, so installing the app does not guarantee that you will be able to request an advance.
03How quickly can I receive money through Rain Instant Pay?
Transfer speed depends on the delivery method selected, your bank or debit card, the employer’s payroll information, and any security reviews. Some transfers may arrive quickly, while standard bank processing can take longer, particularly on weekends or holidays. Before confirming a request, review the estimated arrival time and any applicable charges shown in the app.
04Does Rain Instant Pay charge fees or affect my paycheck?
The cost of using Rain Instant Pay depends on the transfer option and the terms offered through your employer. Some services may provide a free standard transfer while charging for faster delivery or optional features. Any amount accessed is normally reconciled through payroll, which can reduce the wages paid on your regular payday. Always check the in-app fee and repayment details before confirming.
05Is Rain Instant Pay safe to use?
Rain Instant Pay may request sensitive information, including identity, employment, banking, or payment details, so users should review its privacy policy and permissions before signing up. Use the official app-store listing, protect your login credentials, and enable available security features. If you notice an unfamiliar transaction or account activity, contact the app’s support team and your financial institution promptly.


